



Things are changing on the streets of Tokyo. The Bank of Japan has been hiking rates, inflation has buoyed JBG yields, and government spending has increased.
To discuss what one of the biggest macro shifts in years, Jesper Koll, economist, investor, and author of the Japan Optimist Substack, joined us on Macro Sessions to give his boots on the ground perspective.
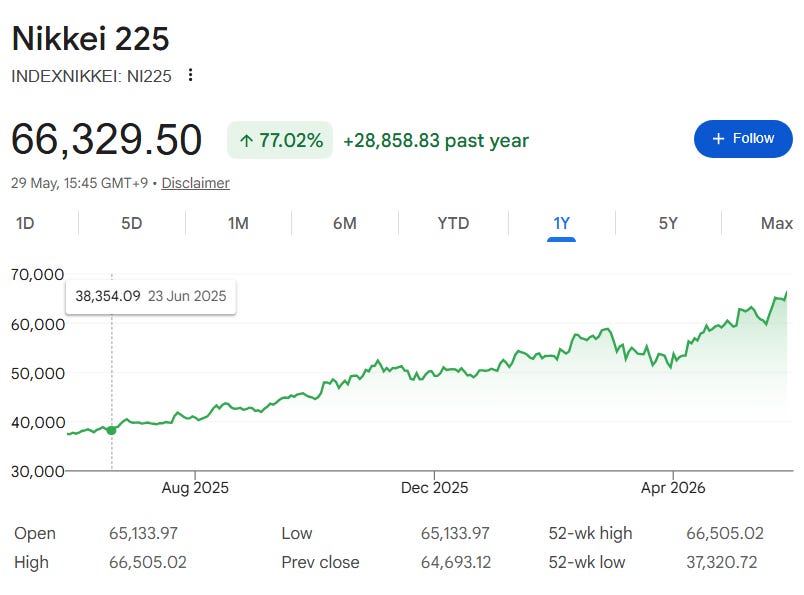
Jesper last joined us on Talking Markets in June 2025 to tell us that Japan was “unbelievably rich” yet “dirt cheap.” At the time, the Nikkei was at around 38,000. Now, it’s 66,329.50. Yup…
🏠Housekeeping note: The first 17 minutes or so are free for everyone to watch, but the full session is available only to paying subscribers. Thank you as ever for all of your support—and if you’re interested in subscribing, you can do so here.
THE NEW WEALTH EFFECT
While official inflation numbers in Japan are dipping, Jesper says that’s largely because of government intervention: “The government is holding and subsidizing gasoline prices, and introducing price reductions for utilities, for example.”
Japanese Prime Minister Sanae Takaichi, who has been in office since October 2025, is essentially fiddling while prices go up. She is “trying to manipulate the inflation data,” Jesper said. “We’re going to get another supplementary budget where the bulk of it is going to be a handout to reduce the impact of rising utility costs on Mr and Mrs Watanabe, which is a weird policy in the sense that you’re not allowing the supply side to actually get creative in, for example, deregulating the utility markets so that some new suppliers can actually start to come in.”
When you look beyond government intervention, “the reality of consumer price inflation accelerating is very strong,” Jesper said. And unlike the past, where it was because of the weak yen, plus rising energy and food prices, this time the drivers are different.
“Over the last six to nine months, [we are seeing] actual pricing power,” Jesper said. “You find that even small and medium-sized companies are increasing prices. A year ago, two years ago, there was still this almost shame if you increase the price of a candy bar or if you increase the price of your meal in your restaurant. That is gone.”
According to Jesper, three distinct engines are firing simultaneously to lift household confidence and drive this demand-pull inflation:
The Wage Revolution: The annual shunto base-pay negotiations have delivered wage increases exceeding 5% for two straight years.
The Youth Premium: Due to severe structural labor shortages, starting salaries for the younger generation shot up by 7% last year and another 8% this year. That’s a ginormous reversal after thirty years of stagnant, zero-growth pay.
The Real Estate Rebound: After a generation of negative wealth effects, property values have firmly bounced back past their historic pre-bubble peaks in the 1980s, making everyday citizens feel significantly wealthier.
ANIMAL SPIRITS AND THE ONSHORING BOOM
Things are changing for more than Joe Public (Or Mr. and Mrs. Watanabe) - the domestic banking system is experiencing a structural awakening.
For the first time in decades, Japan’s money multiplier has turned positive. Banks have reversed a 30-year contraction and are actively lending to both consumers and local corporations.
“We now have animal spirits,” Jesper said. “You’ve got 3 consecutive years of business investment expenditure actually accelerating.”
And it’s not money that’s flowing overseas, it’s happening in Japan. “Geoeconomics plays a very big role because Japanese CEOs now know that if you don’t do it here in Japan, you cannot rely necessarily on the stability of the supply chain. So onshoring is a big factor going forward.”
Jesper contrasted Japan with the US - he said the US economy has become “lopsided” in favor of AI spend, while in Japan, business investment is everywhere:
“…Whether it’s the service sector, the retail sector, the manufacturing sector, all the way from large corporations through to small and medium-sized companies. The basic driver behind all of that is the reality that there is now inflation, that corporations have pricing power, and that banks are willing to lend to you.”
LABOR SHORTAGE REALITY CHECK
Transitioning from decades of economic stagnation to a high-pressure, inflationary environment isn’t a walk in the park. The economy, Jesper said, is “screaming” under the weight of resource constraints:
“Everywhere you look, every CEO I talk to, is struggling because of resource constraints. You want to build a data center here in Japan? Get in line. The waiting line to get a contractor now is over 3 years long.”
This battle to get and retain talent is reflected in wages:
“If you’re in your 20s and 30s in Japan, if you switch jobs, the average increase in pay is 40%, according to recruitment data,” Jesper said.
BANK OF JAPAN “WAY BEHIND THE CURVE”
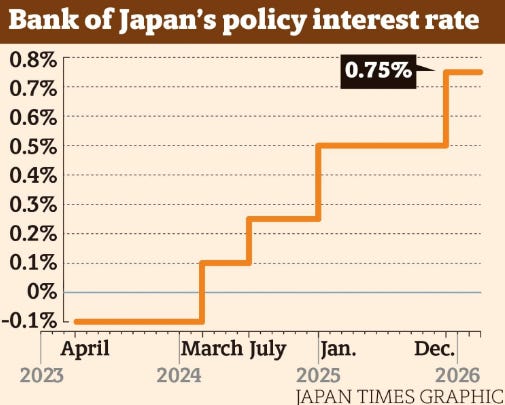
The Bank of Japan’s key short-term interest rate is currently 0.75% - which is at multi-decade highs. The market currently projects that Japan’s neutral policy rate will top out around 1.5%, but Jesper thinks that estimate is far too conservative:
“If you have a growth potential of around 1%, and you’ve got an inflation target of around 2%, then the neutral rate, if you look like something like a Taylor rule, should be somewhere between 2.5-3.5%.. The true neutral rate, in my opinion, is much closer to 2.5-3% percent, and that’s the repricing that is going on in the system.”
Jesper said that a big reason the Bank of Japan has moved slowly on this is due to structural fragilities in the secondary banking system, many of which are losing deposits as an aging rural population shrinks.
But those fragilities are being mitigated - about 8 billion dollars of private equity capital is currently focused on consolidating the secondary banking system. “In other words, you have a white knight in terms of private equity firms wanting to consolidate the financial system,” Jesper said. “Over the next couple of months, we should see one or two headline cases of some of the regional banks actually being integrated.”
❗Once the Bank of Japan is confident that’s going smoothly, he thinks they “get a green light to actually normalize the policy rate.” He predicts a rapid acceleration in the back half of the year, forecasting that the official policy rate will climb from 0.75% today to 2.25% by this time next year.
CLEAN UP IN AISLE ZOMBIE
The consolidation isn’t restricted to regional banks either, meaning that Japan’s long-standing policy of preventing bankruptcies at any cost looks like it’s coming to an end.
Now, the ruling LDP party is “actually confident that you can let the zombie companies go,” Jesper said. “All the conversations I have with the Prime Minister’s office are around creating regional and national champions that can actually compete against [the likes of] Samsung or BYD.”
🪢More from Jesper: Towards National Champions
Private equity also has a role to play here, Jesper said, as do activist investors “sort of nudging the CEOs [about the fact that] they have the capital markets on their side if they have a growth strategy that focuses on consolidating the industry. So there’s a good ecosystem starting to be built here. I don’t expect failures; I do expect consolidation.”
And Jesper also sees megabanks getting involved, pointing out that Sumitomo Bank has bought a 10% stake in SBI group, known as an aggressive relatively new institution.
“I think you will see Japanese mega banks taking more risk by actually starting to do some of that consolidation in the secondary banking system, as well as Japanese megabanks taking the lead in issuing their own stablecoins and starting to raise their independence from the current settlement systems coming through.”
THE BIGGEST RISK OF THIS GOING WRONG
🔒The conversation continues below. Jesper discusses what could change the Japan bull story, why the demise of the carry trade is imminent, Japan’s take on AI, and the sectors of the Japanese stock market he’s keen on. To upgrade your Market House membership and get access to the whole thing, right this way.


